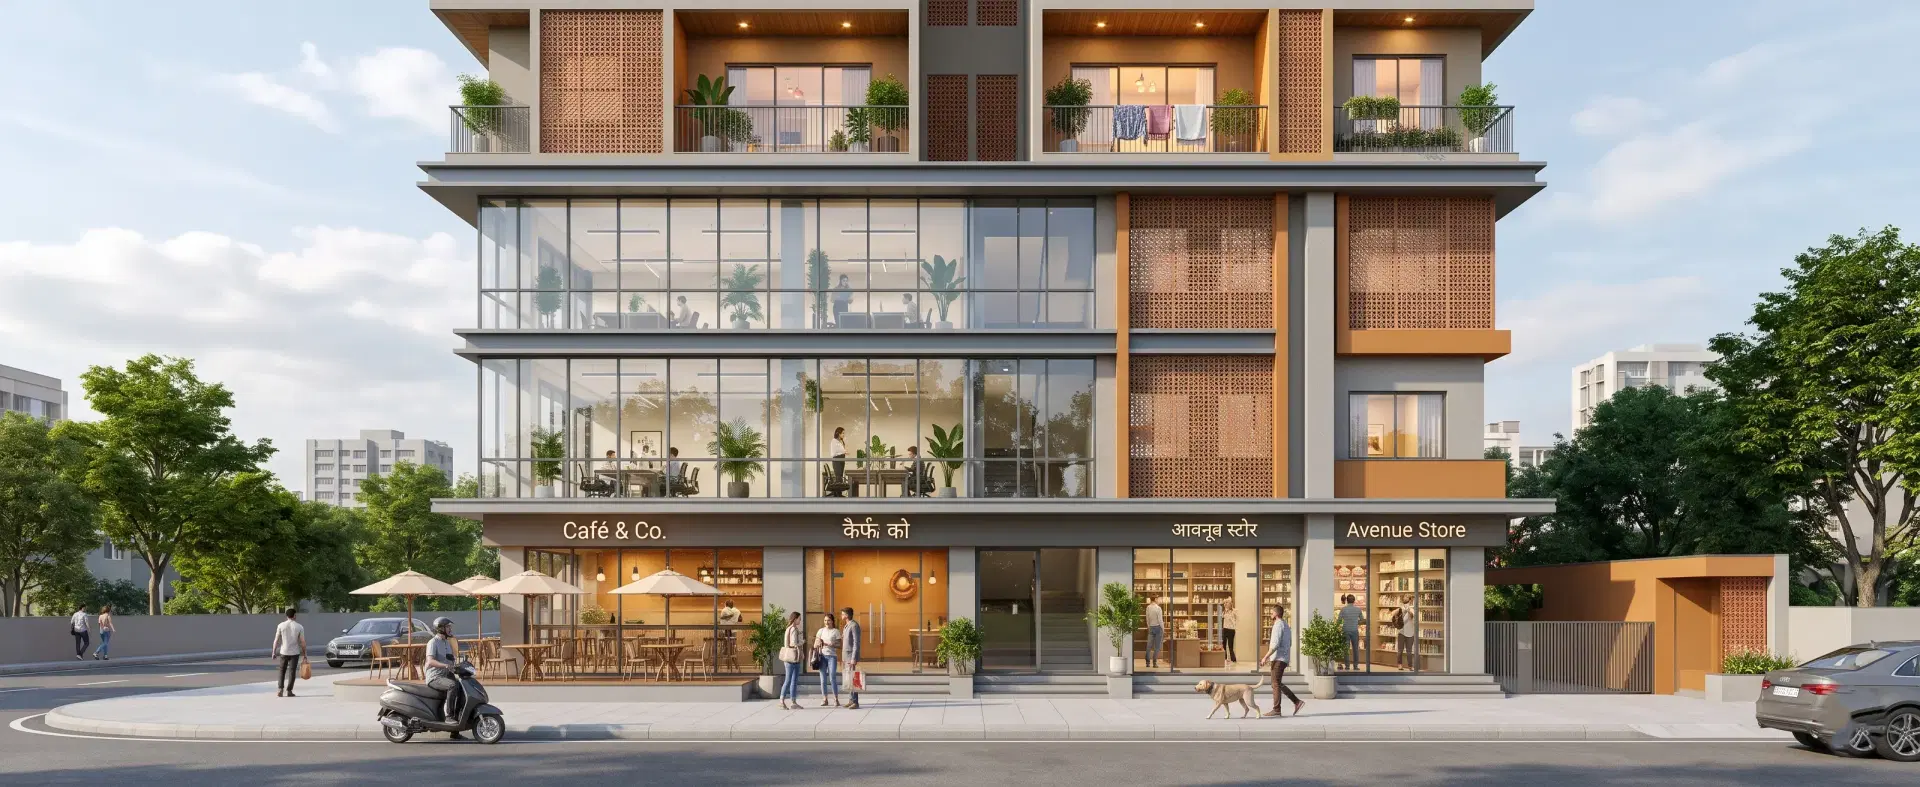
A mixed-use property combines two or more uses, such as apartments, offices, shops and restaurants, in one building or on one planned site. On 10 November 2026, JLL said it had arranged a US$310 million bridge loan for Peabody Union, a 665,000-square-foot mixed-use development on the Cumberland River in Nashville, according to the Mortgage Bankers Association's NewsLink. The deal shows why a mixed-use property is harder to judge than a single apartment block or office building.
Peabody Union holds three businesses under one name. Its office building is fully leased to Starbucks, which moves in during 2027, while its 355 apartments compete for renters and only 49.9% of its shop and restaurant space was leased. For an Indian investor weighing private U.S. real estate, the lesson is that a mixed-use property has to be judged part by part, and then as a whole, because one loan and one sponsor tie the parts together. The main U.S. property types each behave differently, and a mixed-use asset puts several of them in the same place.
What a Mixed-Use Property Is
The term covers a wide range. At one end sits a small building with a shop at street level and flats above. At the other end sits a planned district such as Fields Frisco in Texas, a US$10 billion, 2,545-acre joint venture that includes a corporate headquarters and a resort, according to CRE Daily on 11 November 2026. The same report, citing an analysis by The Real Deal, counted at least US$24 billion of mixed-use projects moving toward construction in Frisco.
Mixed-use schemes come in two broad shapes. In a vertical scheme the uses are stacked, with shops on the ground floor, offices in the middle and homes above. In a horizontal scheme, separate buildings for each use sit on one site, linked by streets, parking and public space. Either way, the uses share land, access and usually one owner and one loan, which is what makes the asset a single investment rather than several.
Why Each Part Earns Money Differently
Each use in a mixed-use property runs on its own kind of lease. Apartment leases are usually short, so rents reset often and income follows the local rental market closely. Office leases tend to run for many years and often include rent-free months and money from the owner to fit out the space. Shop and restaurant leases can link part of the rent to the tenant's sales, and those tenants depend on how many people pass by.
This mix can work in both directions. Residents bring customers to the shops and restaurants, and offices bring daytime visitors, which can support the whole site. Even so, the same links can spread trouble. An empty ground floor makes the apartments above less attractive, and a large office tenant that leaves can weaken the street life that the other uses rely on.
Peabody Union shows the spread clearly. One part has a single long-term office tenant, one part depends on hundreds of individual renters, and one part was about half leased when the loan was arranged. An investor reading such a deal would want to know how much of the net operating income, meaning rent minus running costs, comes from each part, and how much is backed by signed leases. A rent roll for a U.S. property is the document that lists those leases.
How Lenders Look at a Mixed-Use Building
Lenders do not treat every square foot the same way. Freddie Mac's Multifamily Seller/Servicer Guide, in Section 8.2(b) as updated on 20 October 2026, compares both the income and the floor area from commercial space with the whole property, and says both must be acceptable to Freddie Mac. The same section requires the commercial use to be permitted under local zoning and its rent to be supported by market comparison.
As a result, the debt available for a mixed-use property can depend on its least familiar part. A building that is mostly apartments may qualify for loans designed for apartments, while one with a large office or shop component may need a different lender, different terms or more equity. Peabody Union's loan runs for three years with two one-year extension options, according to the MBA report. A bridge loan in real estate is short-term debt that is usually replaced later, so its terms deserve close attention.
The Risks and Limits of Mixed-Use Property
The first risk is uneven leasing. One part can be full while another sits partly empty, and the weaker part may need years of effort and fresh spending on fit-outs before it covers its share of costs. The second is complexity. A mixed-use property needs a sponsor, meaning the firm that buys and runs the deal, with skill in several property types at once, and weakness in any one of them can hold back the whole asset.
The third risk is debt. If the loan comes due before every part is stable, the owner may have to refinance on worse terms, add equity or sell. Property values can fall, tenants can leave, distributions to investors may be reduced or not paid, and investors can lose capital. Private real estate is also illiquid, so an investor usually cannot sell a stake easily before the property itself is sold.
Indian investors face further risks. Rent is earned in dollars, so its value in rupees moves with the exchange rate between the rupee and the dollar, in either direction. Money sent abroad under the Liberalised Remittance Scheme counts toward the limit of US$250,000 per resident individual per financial year. Tax applies in both the U.S. and India, as the guide to U.S. real estate tax for Indian investors explains. Concentration matters too, because one large mixed-use asset can tie much of a portfolio to one city.
What to Check in a Mixed-Use Deal
The offering documents for a private U.S. deal should answer a short set of questions about each part of the property and about the structure around it.
- How much of the income comes from each use, and how much of it is under signed leases.
- When the main office and shop leases end, and whether any single tenant pays a large share of the rent.
- Whether the sponsor has run apartments, offices and shops before, and in this market.
- When the loan matures, whether it has extension options, and what conditions those options carry.
- How the property is held, for example through a U.S. corporation that owns the property interest, and which U.S. tax forms the investor will receive.
Answers to these questions do not remove any risk. They show where the risk sits, which is the first step in deciding whether a mixed-use property fits an investor's wider portfolio.
One Address, Several Businesses
A mixed-use property can look like a single building on a map, yet it behaves like several businesses sharing one loan and one manager. Peabody Union's fully leased office, its apartments and its half-leased shop space show how far apart those parts can sit at the same moment. That gap, more than the design or the location, is what an investor needs to understand.
The more useful approach is to read each part on its own terms and then ask how the debt and the sponsor connect them. Raveum's guide to the U.S. real estate market gives the background on each property type. Eligible investors can review how investing in U.S. real estate from India works on Raveum, including the property, sponsor, ownership structure, fees, risks and offering documents for each opportunity.
Frequently asked questions
What is a mixed-use property?
A mixed-use property combines two or more uses, such as apartments, offices, shops and restaurants, in one building or on one planned site. The uses can be stacked in a single tower or spread across separate buildings. They usually share land, access, an owner and one loan, so investors treat them as a single asset.
Is a mixed-use property riskier than an apartment building?
It carries different risks rather than simply more of them. A mixed-use property depends on several leasing markets at once, so one weak part can hold back the whole. It also needs a sponsor skilled in more than one property type. An apartment building is simpler to judge but depends on one kind of demand.
How are mixed-use properties financed?
Lenders look at how much income and floor area comes from commercial space. Freddie Mac, for example, says both shares must be acceptable to it. A property with a large office or shop component may need a different lender, short-term debt such as a bridge loan, or more equity than an apartment building would.
What are the disadvantages of mixed-use development?
Mixed-use development is complex to plan, build, lease and manage. Its parts often lease up at different speeds, so income can trail costs for years. Zoning approvals, shared services and several types of tenant add work. If the loan comes due before every part is stable, refinancing can be harder and costlier.
How is a mixed-use property valued?
Valuers usually look at the income from each use separately, because apartments, offices and shops carry different rent levels, vacancy and lease lengths. They then combine the parts and allow for shared costs. Investors should check whether each part's rent is supported by comparable properties nearby, and how much depends on space not yet leased.
Can Indian residents invest in U.S. mixed-use property?
Indian residents can send money abroad for investment under the Liberalised Remittance Scheme, within its limit per financial year, and their bank reviews each transfer. Private U.S. offerings are limited to eligible investors, are illiquid and can lose value. Investors should discuss tax, currency risk and suitability with their CA and adviser first.
This article is for general education only and is not investment, tax or legal advice. Rules change and depend on individual circumstances. Investing in private real estate involves risk, including loss of capital, illiquidity, falling property values, distributions not being paid and currency movements. Participation is limited to non-U.S. persons under SEC Regulation S and verified U.S. accredited investors under Regulation D Rule 506(c), and offerings on Raveum are not open to the general public.
