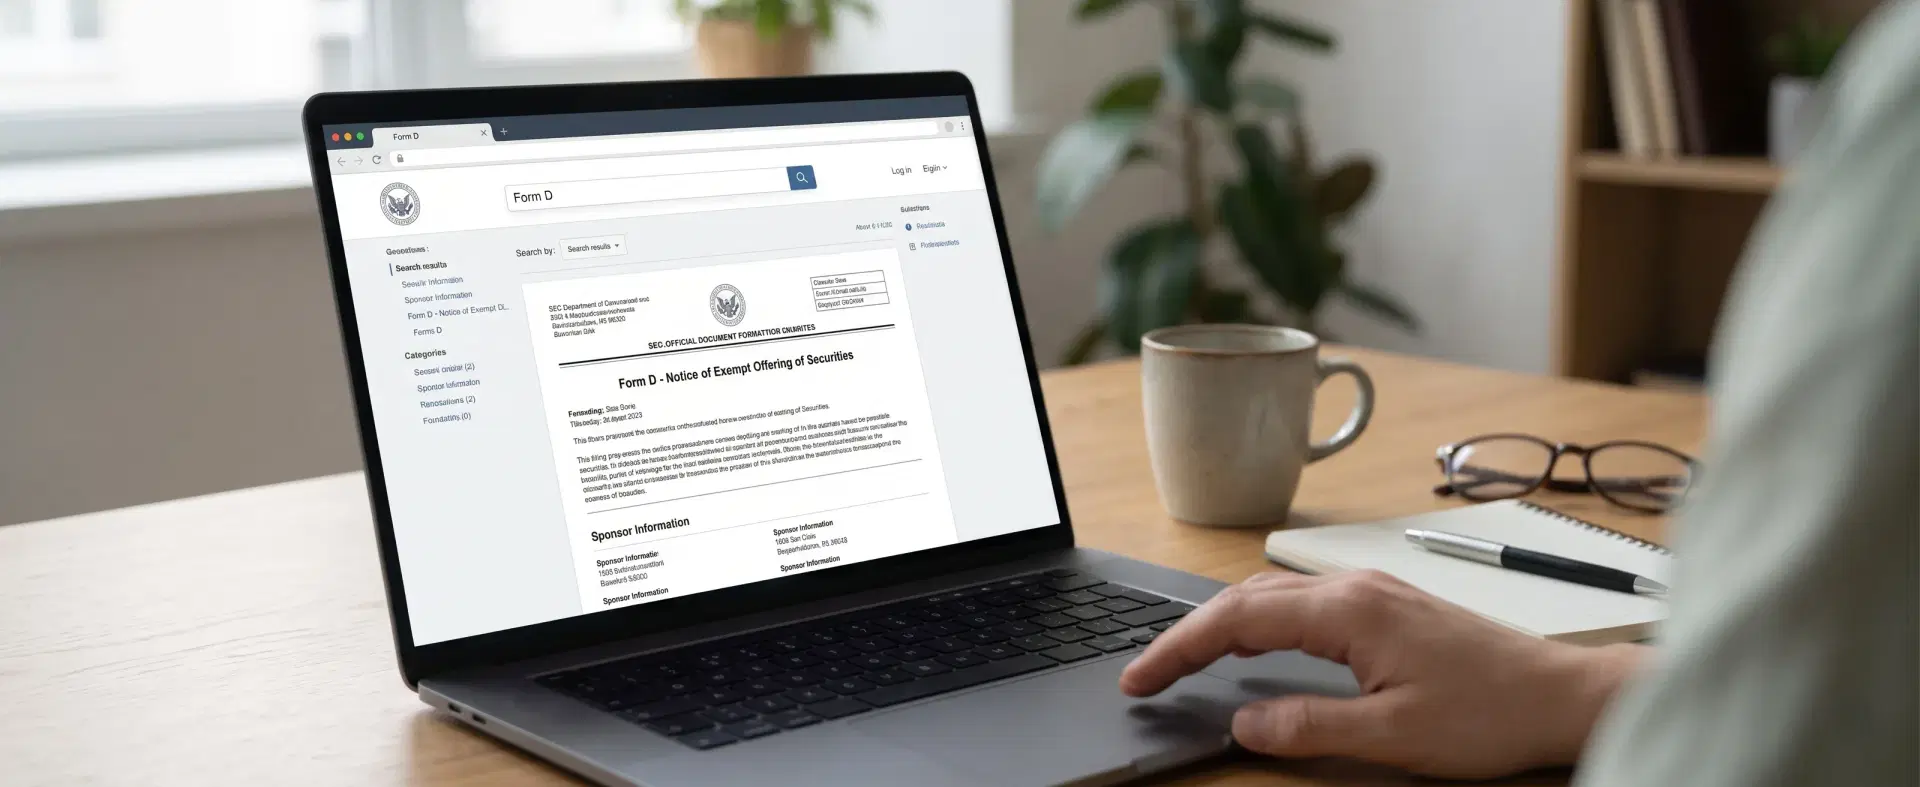
On October 29, the SEC charged two entities over a scheme that it says raised more than $130 million. According to the complaint, the two submitted false Form ADV and Form D filings. They then showed those filings to investors as proof that the SEC had licensed or approved them. The case concerns crypto trading, not property, and its claims are allegations that a court has yet to decide. Even so, it shows that a form D search on EDGAR has become a first check on a private raise, and how easily that check is misread.
For a real estate sponsor, the lesson runs in the other direction. A Form D is often the only public trace of a private raise. Investors, family offices and advisors who look a sponsor up may read it before the deck. The filing approves nothing, yet it says a good deal about how a sponsor runs its offerings. A sponsor that keeps the record accurate and consistent, and never presents it as more than a notice, turns a routine form into evidence of discipline. That record sits inside the wider process set out in the 506(c) capital raise checklist.
What a Form D Search Shows About a Raise
Anyone can run the search. The SEC's Form D questions and answers say that all Form D filings are publicly available on its website. Once made, a filing generally cannot be withdrawn. The SEC's bulletin on private placements tells investors they can search EDGAR for the Form D of any offering with prior sales. In practice, a reader types the issuer's name into EDGAR and sees every notice and amendment that entity has filed.
What the reader finds is more detailed than many sponsors expect. The form names the related persons, meaning the executive officers, directors and promoters behind the issuer. It records the industry group, with real estate split into commercial, construction, residential, REITs and finance, and other real estate. It shows the exemption claimed, the date of first sale, the total offering amount and the amount sold. It also shows how many people have invested, how many are not accredited and any proceeds paid to the people behind the deal.
Why a Notice Is Not an Endorsement
The SEC has warned investors about this confusion for years. Its investor alert of April 30, 2019, Beware of Claims That the SEC Has Approved Offerings, calls a Form D merely a notice to the SEC and the public. The alert adds that fraudsters may use Form D to claim falsely that an offering was registered or approved. The SEC's updated bulletin on private placements is plainer still, stating that Form D does not represent SEC approval or registration.
The October complaint describes exactly that pattern, which is why the distinction now matters to honest sponsors as well. An allocator who has read about the case will treat any suggestion of SEC endorsement as a warning sign. Careful wording therefore protects a sponsor's credibility as much as its compliance. A sponsor can say that it filed a notice of an exempt offering under Regulation D. The words registered, approved and licensed stay out of decks, emails and websites unless they describe something else that is true, such as a broker's own registration.
How Investors Read the Record Across Deals
Most sponsors form a new entity for each deal, so a form D search on the sponsor's name rarely stops at one filing. A reader can follow the same principals through a series of notices. The reader can see when amendments arrived and whether the exemption claimed matches the marketing. Gaps and contradictions stand out quickly when filings are read side by side. A deck that describes an open 506(c) raise, for example, sits awkwardly beside a notice with the 506(b) box checked.
The search does not end at the SEC either. Many states take Rule 506 notice filings through the NASAA Electronic Filing Depository. At its launch, NASAA said the system lets the public search and view Form D filings free of charge. Professional allocators such as family offices and wealth managers are the readers most likely to run both searches. For a sponsor trying to expand its investor base beyond its own network, the public record is often a new investor's first impression.
Keeping the Public Record Consistent With the Raise
Rule 503 sets the update cycle. Under the rule, a sponsor amends the notice as soon as practicable to correct a material mistake or to reflect certain changes. It also amends on or before the first anniversary of the most recent filing while the offering continues. The rule lists changes that need no amendment, and the amount sold and the number of investors are among them. A search can therefore show figures that lag the live raise, which is normal but worth explaining before an investor asks.
The SEC's Form D answers confirm that filing is not a condition of the Rule 506(b) or 506(c) exemption. That does not make accuracy optional. The signature block on the form warns that intentional misstatements or omissions of fact constitute federal criminal violations. Consistency is mostly a records task. The related persons, amounts and dates on the notice should match the subscription documents and the investor ledger. That is the kind of work a sponsor can keep in house or hand to real estate fund administration. The filing mechanics themselves, from deadlines to state notices, are covered in the guide to the Form D SEC filing.
What Sponsors Can Do Before the Next Form D Search
Most of this is easiest to settle before the next notice goes in, with securities counsel reviewing the choices. The steps below follow the order in which a reader would meet them.
- Run a form D search on every entity the sponsor has used and note any filing that looks inconsistent or out of date.
- Check that the related persons, exemption box and offering amount on each live notice match the current offering documents.
- Put each annual amendment date in the raise calendar and review the notice whenever the team or the offering amount changes.
- Remove any wording in decks, emails or web pages that could suggest the SEC registered, approved or reviewed the offering.
- Prepare a short, accurate explanation of why figures on EDGAR may trail the live raise, for investors who ask.
Raveum offers sponsors four solutions. They are an investment management platform, fund administration, a global raise track under Regulation S and an operating partnership for selected sponsors. U.S. investors come in under Rule 506(c) and receive K-1s, and sponsors keep their investor relationships, their property and their business plan. See how the Raveum Sponsor Program works.
The Public Trace of a Private Raise
The October 29 complaint will be argued in court, and its allegations may or may not be proved. Its lesson for sponsors does not depend on the outcome. Investors already treat a Form D as something to check, and the SEC has told them it is a notice, not an approval. A sponsor gains most by meeting that reader halfway, with a record that is accurate, current and consistent with everything else it says. In a private market where so little is public, the notice is where that care shows. It belongs in the same plan as the verification and marketing steps in the 506(c) capital raise checklist.
Frequently Asked Questions
How Do You Run a Form D Search on EDGAR?
Go to the SEC's EDGAR company search and enter the issuer's name, which for a syndication is usually the deal entity rather than the sponsor brand. The results list every filing by that entity, and the notices appear as Form D, with amendments marked D/A. The SEC says all Form D filings are publicly available, so no login is needed to read them.
What Can Investors Learn From a Form D Filing?
A Form D shows the issuer, its executive officers, directors and promoters, the industry group and the exemption claimed, such as Rule 506(b) or 506(c). It also shows the date of first sale, the total offering amount, the amount sold, the number of investors and any proceeds paid to related persons. It does not show the property's business plan or the risks.
Does a Form D Filing Mean the SEC Approved the Offering?
No. The SEC's investor alert says a Form D is merely a notice to the SEC and the public, and its private placement bulletin says the form does not represent SEC approval or registration. The SEC never approves an offering. A sponsor should avoid any wording that suggests otherwise, and securities counsel should review marketing material before it is used.
Can a Sponsor Withdraw a Form D After Filing It?
Generally not. The SEC's Form D answers say that once filed, a Form D is publicly available on EDGAR and generally cannot be withdrawn. A notice with an error is corrected through an amendment, which Rule 503 requires as soon as practicable after the mistake is found. The original filing stays visible beside the amendment, so accuracy at the first filing matters.
Where Can Investors Search State Form D Notice Filings?
Many states receive Rule 506 notice filings through the NASAA Electronic Filing Depository. NASAA said at launch that the system lets the public search and view Form D filings free of charge, and its search screen accepts an issuer name, CIK number or accession number. Not every state uses the depository, so counsel should confirm where each notice was filed.
Why Might Form D Figures Differ From the Live Offering?
Rule 503 does not require an amendment for every change. A change in the amount sold, the number of investors or a related person's address, for example, needs no amendment by itself. Figures on EDGAR can therefore trail the live raise until the next required amendment, including the annual one. A sponsor can explain this to investors rather than leave the gap unexplained.
This article is for general education only and is not legal, tax or investment advice. Securities and tax rules change and depend on each sponsor's facts, so work with qualified securities counsel and tax advisors before launching an offering. Real estate investments involve risk, including loss of capital, illiquidity and changes in property values. Offerings on Raveum are available to eligible investors only and are not open to the general public.
